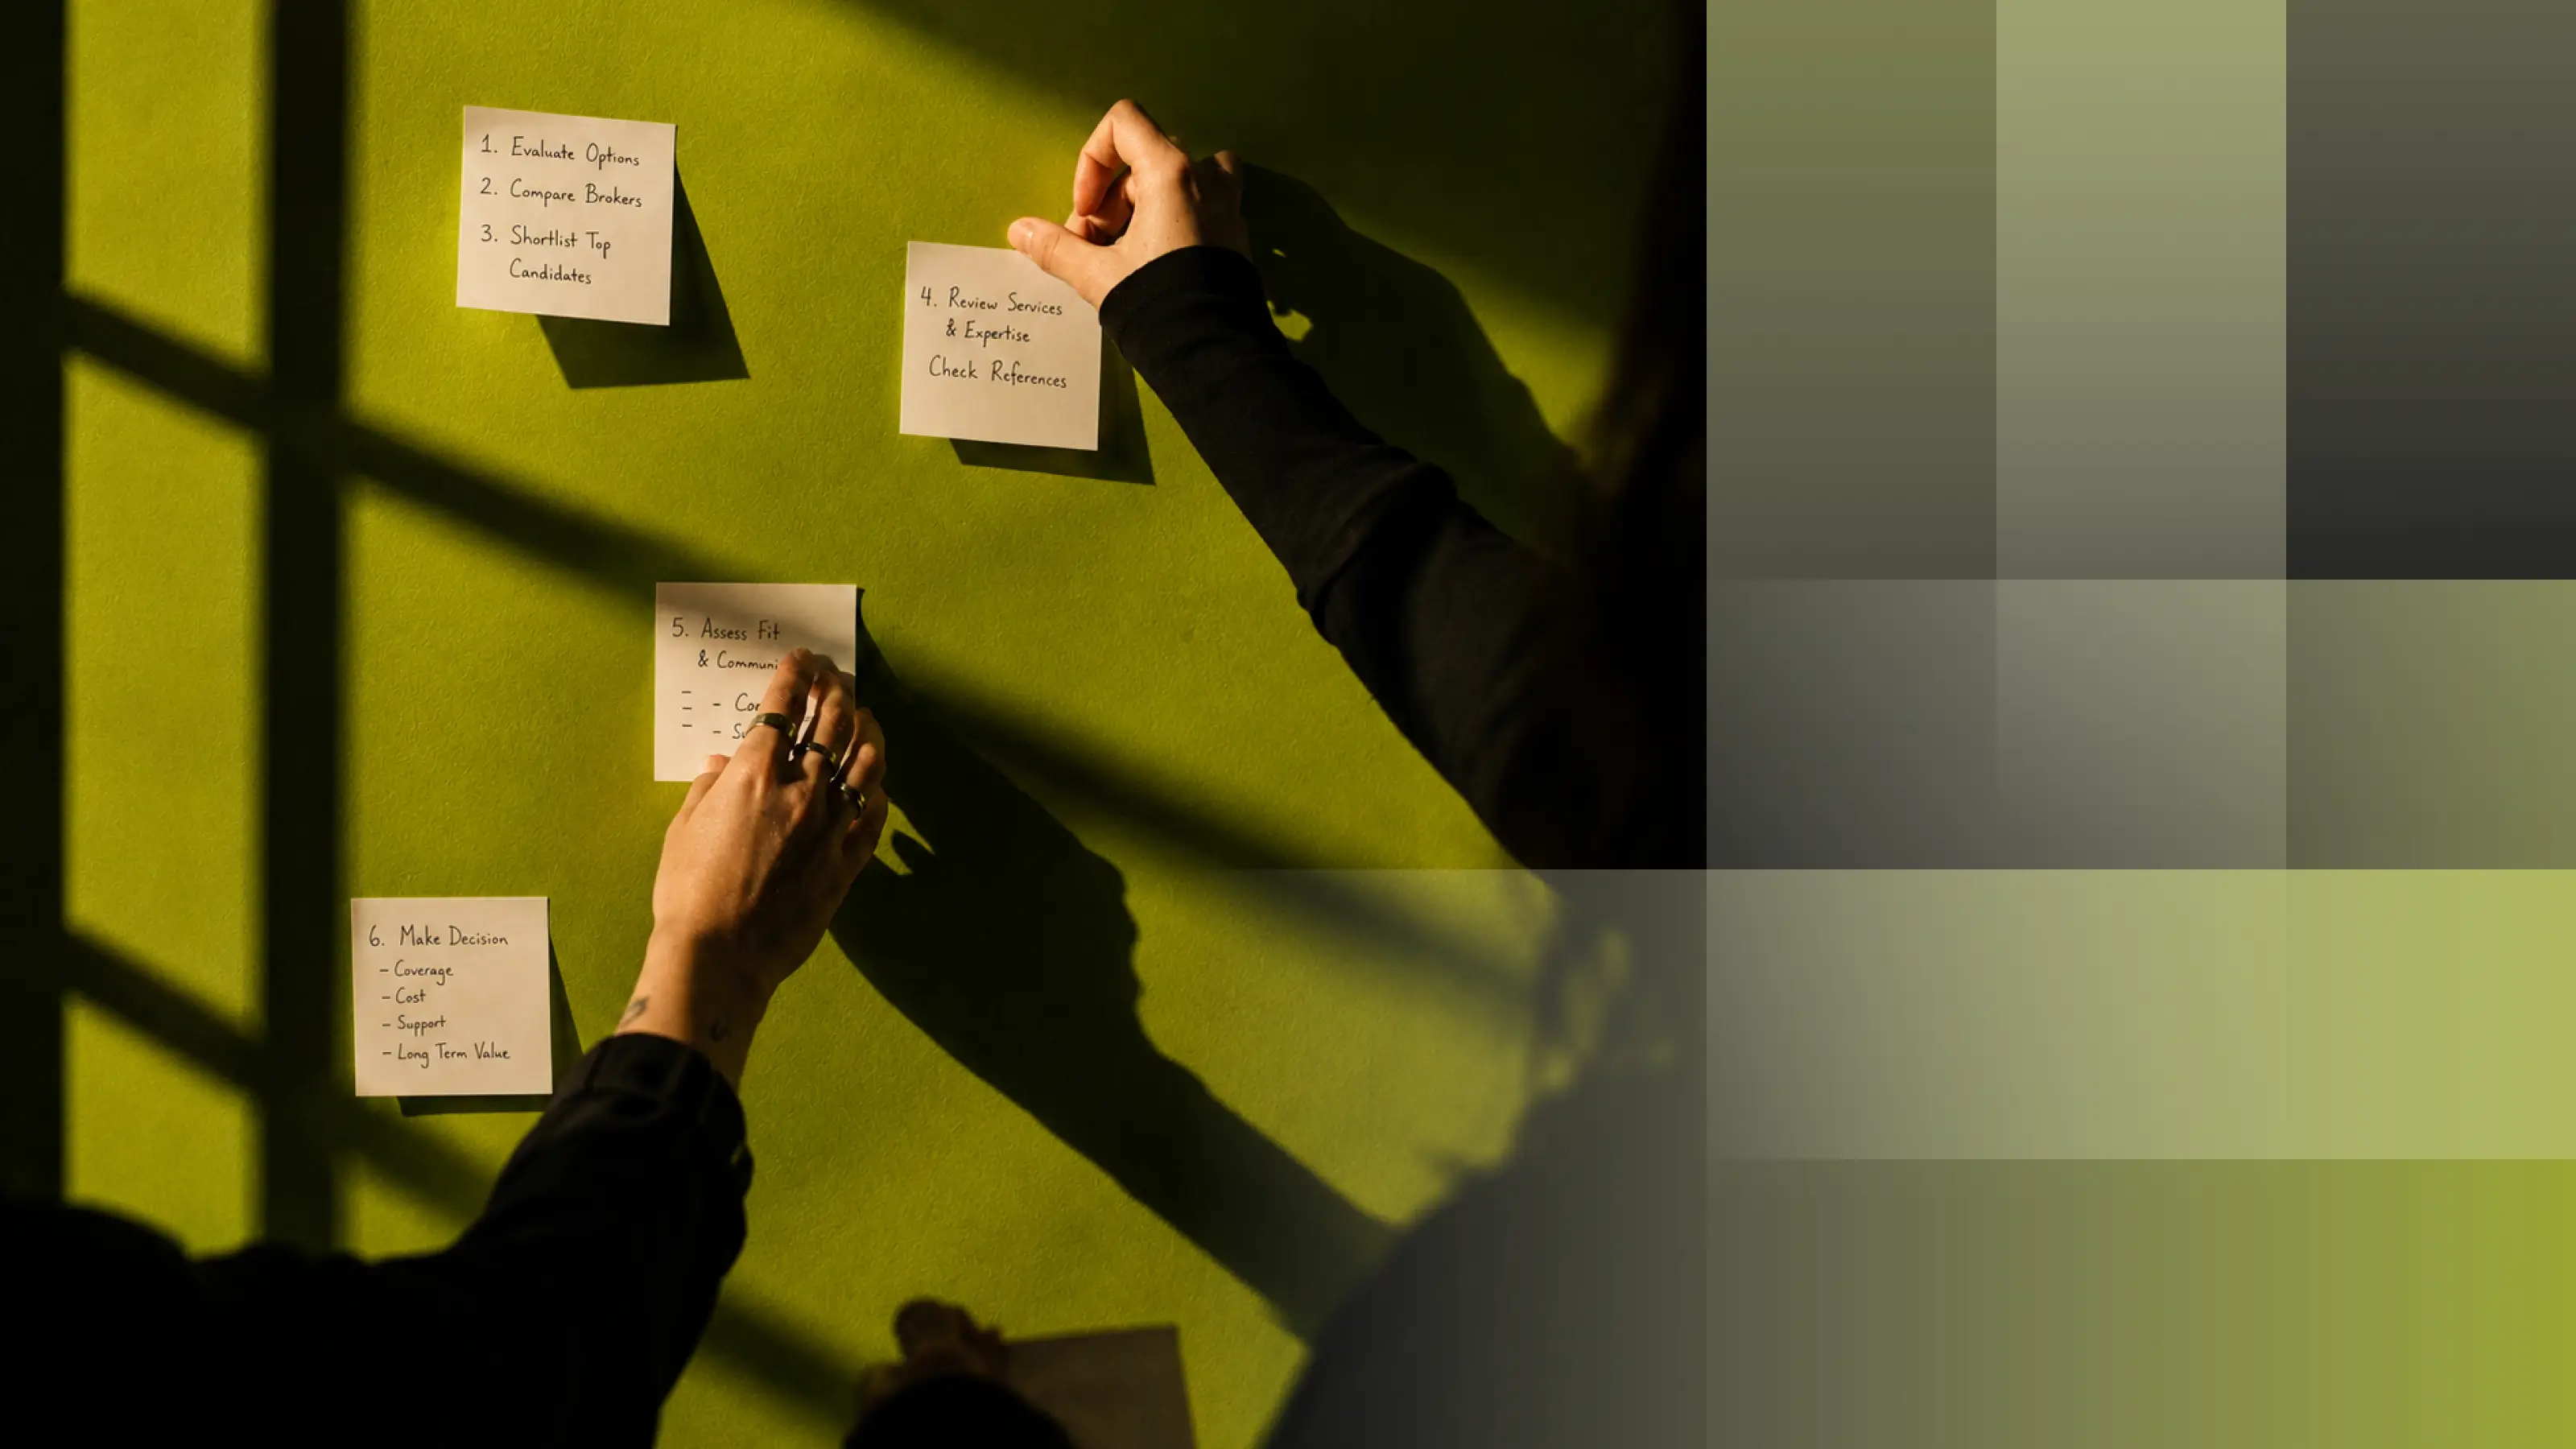



- The renewal process runs about 120 days. You gather data, receive the carrier's offer, benchmark it, take it to other carriers, decide on plan design and contributions, then enroll employees before the plan date.
- The renewal letter is a starting offer. Carriers in states like Texas must send a small group rate increase at least 60 days before it takes effect, and you can negotiate after it arrives.
- Most employers skip the steps that save money. 48% of Small and Midsize Businesses (SMBs) paid at or close to the first number their insurer quoted, and 38% compared two or fewer carriers.
- Starting late removes your options. Remarketing the plan, changing the funding model or leaving a Professional Employer Organization (PEO) all need lead time.
Your renewal letter shows up with a double-digit increase and a deadline a few weeks away, so signing feels like the only option.
The employee benefits renewal process is the 90 to 120 days before your plan date when you review your current plan, compare it with the market, negotiate the rate and enroll employees for the next year. Run it on schedule and you keep every option open.
This guide covers the benefits renewal timeline, the six steps of the process, how to read your renewal letter and what to do besides accepting the increase.
What the Employee Benefits Renewal Process Is
The employee benefits renewal process is the annual cycle in which your group health plan, and usually dental, vision and life coverage, is repriced and renewed for another plan year. It ends when employees are enrolled in the new year's coverage.
Four parties take part:
- The carrier prices the renewal from your claims, census and market trend.
- The broker reviews the offer, quotes other carriers and negotiates.
- The employer sets the plan, budget and contributions.
- Employees choose coverage during open enrollment.
At renewal, four things can change: your rates, your plan design, what employees contribute and which carrier you use. Ignition's renewal service covers each one, and our list of top benefits brokers compares how other brokers handle it.
If your benefits run through a PEO, you renew on the PEO's calendar and see far less of this process. The PEO negotiates for its whole pool, so you get the result without the breakdown.
Benefits Renewal Timeline: 120, 90, 60 and 30 Days Out
Work backward from your plan date. Find the row that matches where you are today.
120 Days Out: Prepare Your Data
Pull together your employee census, your current plan documents and any claims reports your carrier or broker can provide. Decide whether you'll take the plan to market this year.
If you plan to change brokers, do it now, while the new broker still has time to quote the full market.
90 Days Out: Benchmark and Go to Market
Your broker compares your cost per employee and plan design with similar companies. Then they send your census to other carriers for quotes, including level-funded and self-funded options if your team's risk profile supports them.
60 Days Out: Receive and Negotiate the Renewal
The carrier's group health insurance renewal offer usually arrives around now. In Texas, insurers must give small employers written notice at least 60 days before a rate increase takes effect, and they can't require a response before the 45th day after the notice. Virginia requires 60 days' notice for group increases above 35%. Use competing quotes to negotiate.
30 Days Out: Decide and Enroll
Finalize the plan and contributions, then run open enrollment. If your plan renews automatically, your carrier or plan must give employees a Summary of Benefits and Coverage (SBC) no later than 30 days before the new plan year.
Most employers never get a full view of this timeline. Only 31% of SMBs received a clear breakdown of what drove their last renewal increase, and 39% took a double-digit increase (Benefits Blind Spot).
The Employee Benefits Renewal Process in 6 Steps
The health insurance renewal process for employers follows the same six steps at 15 employees or 150. Use the bolded item in each step as your benefits renewal checklist.
Step 1: Gather Your Census, Claims and Plan Documents
Carriers price your renewal on your census and claims, and brokers need the same data for competing quotes.
- Have ready: An employee census with each employee's date of birth, gender, ZIP code and coverage tier, plus your current Summary of Benefits and Coverage and any claims reports.
Step 2: Review the Renewal Offer
Read the rate change, the reasons given and any plan changes, and compare the new premium with last year's. The next section shows how to read the letter line by line.
- Have ready: The renewal letter and its rate exhibit, which lists current and new premiums by plan and coverage tier.
Step 3: Benchmark Your Plan
A benchmark tells you whether your renewal is reasonable for a company your size, location and risk profile. CFOs who benchmark regularly are nearly twice as likely to say they manage healthcare costs effectively, and none of them reported feeling stuck, according to a 2026 survey of nearly 150 CFOs by CFO Leadership Council and Ignition. Only 39% of respondents benchmark regularly.
Start with your own numbers using our cost of benefits per employee calculator and employee cost calculator.
- Have ready: Your current total cost per employee per year.
Step 4: Market the Plan to Other Carriers
Your broker sends your census to every carrier in your state for quotes on matching plans. Without other quotes, your carrier has no reason to move. Ask for quotes across funding models too. Our guide to level-funded vs. fully insured plans explains the difference.
- Have ready: A list of every carrier quoted and a side-by-side comparison of their prices.
Step 5: Decide Plan Design and Contributions
Choose the plans you'll offer, the deductibles and how much of the premium you'll pay. These choices affect hiring as much as cost. 53% of SMBs say rising healthcare costs have made it harder to compete for talent (Benefits Blind Spot).
Small company employees already pay more. At firms with 10 to 199 workers, employees paid $9,687 a year for family coverage in 2026, or 37% of the premium (KFF). For other ways to manage cost, see our guide on how to reduce small business health insurance costs.
- Have ready: A per-employee benefits budget for the new plan year.
Step 6: Communicate and Enroll Employees
Before open enrollment, tell employees what's changing, send the SBCs and set a firm deadline. Then submit final enrollment to the carrier before the plan date.
- Have ready: SBCs for every plan offered and a written enrollment deadline.
How to Read Your Renewal Letter
A renewal letter has four parts. Here's what to look for in each:
RENEWAL NOTICE: [Group name], plan year starting 1/1/2027
1. RATE ACTION
Current monthly premium: $48,200
Renewal monthly premium: $55,430 (+15.0%)
--> Check: is this total, or per plan? Compare tier by tier.
2. REASONS FOR THE CHANGE
Medical trend: +9.0%
Group experience: +4.5%
Demographic change: +1.5%
--> Ask: what claims drove "experience," and are those
people still on the plan?
3. PLAN CHANGES (in the plan summary)
Deductible: $2,000 --> $2,500
Specialist copay: $50 --> $60
--> This is a hidden increase. Employees pay more even
if the premium were flat.
4. DEADLINE
Signed renewal due: 11/15/2026
--> Count back: does this leave time to compare quotes?
Figures are illustrative.
Carriers don't always explain good years either. "We often see significant premium increases despite having a favorable claims year," Jeremiah Swett, CFO of Black Label Marine Group, said in the CFO Leadership Council and Ignition survey.
If you're working out how to negotiate benefits renewal terms, start here. Within 48 hours of receiving the letter, send these questions to your broker:
- How much of the increase is market trend, and how much is our own claims?
- Did one or two large claims drive the experience piece?
- How much comes from census changes in age or location?
- What plan, network or pharmacy changes are included?
- How many carriers have you quoted, and can we see every quote?
- What would level-funded or self-funded pricing look like for our group?
- What's the last date we can change carriers or plans?
Did you know? Brokers are often paid a percentage of your premium. When the premium rises 15%, a percentage-based commission rises 15% too. Estimate what your broker earns with our health insurance broker commission calculator.
Your Options Beyond Accepting the Renewal Increase
Most employers treat the renewal as take it or leave it. 48% of SMBs paid at or close to the first number their insurer quoted. When costs rose, 48% shifted the increase onto employees and only 27% absorbed it. Many never saw the alternatives: 19% aren't familiar with Individual Coverage Health Reimbursement Arrangements (ICHRAs), level-funded or self-funded plans, and another 30% have never considered them (Benefits Blind Spot).
You have five options besides signing. Each needs a different amount of lead time.
1. Remarket the Plan to Other Carriers
Your carrier prices the renewal knowing whether anyone else is quoting. Competing quotes change that math. 38% of SMBs compared two or fewer carriers at their last renewal, which left the incumbent's number unchallenged.
- Send the same census to every carrier that writes group coverage in your state.
- Ask for quotes on a matching plan design so you compare price, not benefits.
- Take the best competing quote back to your incumbent with a deadline to respond.
AWM's renewal quote came in at $718,457. After Ignition modeled the group's actual risk and took the plan to market, AWM paid $561,543, kept its existing providers and added the Mayo Clinic Care Network (AWM story).
Trade-off: A new carrier can mean a new network. Check your employees' main doctors before you switch.
Best fit: Any employer whose plan hasn't been quoted elsewhere in two or more renewals.
2. Change Plan Design or Contributions
You can lower premium by changing what the plan covers or who pays for it. The main levers:
- Deductibles and copays: Higher cost sharing lowers premium.
- Plan options: A low-cost base plan with a richer buy-up plan lets employees choose.
- Networks: A narrower network, such as a Health Maintenance Organization (HMO), usually costs less than a broad one.
- Contribution split: Pay a higher share for employee-only coverage and a lower share for dependents.
- Rating method: Composite rates charge one price per coverage tier, so your cost doesn't rise each time an employee has a birthday. Light Labs moved from age-banded to composite rates in its 2026 renewal (Light Labs story).
Marsh found that 59% of employers plan cost-cutting plan changes for 2027.
Trade-off: Most of these moves shift cost to employees. Employees at small firms already pay 37% of the family premium (KFF), and 53% of SMBs say rising healthcare costs make hiring harder. Model the paycheck impact for a single and a family employee before you decide.
Best fit: Employers that need relief this year and can protect the core plan employees value most.
3. Change the Funding Model
A fully insured plan pays the carrier a fixed premium, and the carrier keeps any surplus. Two alternatives let you keep more of what you don't spend:
- A level-funded plan charges a fixed monthly amount for expected claims, administration and stop-loss insurance, which caps your exposure to large claims. If claims come in low, part of the surplus can come back to you.
- A self-funded plan pays claims directly, with stop-loss above a set amount.
These models are already common at small firms. Among covered workers at firms with 10 to 199 employees, 38% are in level-funded plans and 25% are in self-funded plans (KFF). In the Benefits Blind Spot survey, fully insured plans cost $8,005 per employee, compared with $5,914 for level-funded or self-funded plans.
Trade-off: Your costs follow your claims. A bad claims year raises next year's price, and the carrier will underwrite your group before quoting.
Best fit: Younger, healthier teams of 10 or more whose risk profile is better than their fully insured premium suggests.
4. Move to an ICHRA
An ICHRA gives each employee a tax-free monthly allowance to buy individual coverage. You set the allowance by employee class, and employees choose their own plans. Learn the setup in our ICHRA guide.
Two federal rules shape the timing and the math, according to HHS guidance:
- You generally must give employees written notice at least 90 days before the ICHRA plan year starts.
- Employees who accept the ICHRA can't also claim a premium tax credit for Marketplace coverage.
Trade-off: Your budget becomes predictable, but employees carry the price of individual plans. Insurers raised Marketplace prices 26% on average in 2026 (KFF), so check local premiums before you set the allowance.
Best fit: Distributed teams across many states, or groups whose small group quotes run well above local individual market prices.
5. Leave a PEO
A PEO prices your benefits with every other client in its pool, so a healthy team pays for others' claims. Companies on PEOs were more likely than companies working directly with a carrier or broker to take a double-digit increase (49% vs. 34%) and twice as likely to delay or cancel hires to cover it (23% vs. 10%) (Benefits Blind Spot).
- Check your PEO contract for its termination notice period.
- Line up a payroll and HR platform, since the PEO bundles both with benefits.
- Time the new plan's start date to the day PEO coverage ends, so employees have no gap.
See how a PEO transition works and what to expect when leaving a PEO.
Trade-off: You take on payroll and HR tasks the PEO handled.
Best fit: Companies at or near 50 employees with a healthy workforce on PEO pricing.
Common Renewal Mistakes to Avoid
- Starting when the letter arrives: In Texas, a carrier can deliver a small group increase as little as 60 days out, which leaves too little time to quote and underwrite alternatives. Start at 120 days (Step 1).
- Treating the first number as final: 48% of SMBs paid at or close to their insurer's first quote, even though Texas law expressly lets small employers negotiate rates after the notice arrives. Come back with competing quotes (Step 2).
- Judging the renewal on premium alone: A flat premium paired with a deductible jump from $2,000 to $2,500 is still an increase for your employees. Compare premium, deductibles and out-of-pocket limits together (Step 2).
- Never seeing alternatives: 38% of SMBs compared two or fewer carriers, and 49% either don't know or have never considered other funding models. Ask for quotes across carriers and funding types (Step 4).
- Changing brokers after the renewal arrives: A new broker needs 60 to 90 days to collect data and market the plan. Appoint them at the 120-day mark (120-day milestone).
- Leaving employees out until enrollment: If your plan renews automatically, employees must get SBCs at least 30 days before the plan year, and anyone who misses enrollment usually waits a full year. Announce changes before open enrollment opens (Step 6).
Take Control of Your Benefits Renewal With Ignition
Your renewal is the one point each year when you can move carriers, change funding or renegotiate the price. Most employers lose that chance by starting after the letter arrives.
Ignition's free 15-minute review shows where your plan stands against peer companies and what your carrier sees in your data. Learn more about working with Ignition as your employee benefits broker.
FAQs
How Long Does It Take for Insurance to Be Renewed?
Usually 90 to 120 days from first review to enrollment. The carrier's offer typically arrives about 60 days before the plan date.
What Is the Grace Period for Renewal?
Usually 31 days for group health premiums. States such as Delaware require group policies to include a 31-day grace period.
What Happens if You Don't Enroll in Benefits on Time?
You usually wait until the next open enrollment. Losing other coverage, marriage or a new child opens a 30-day special enrollment window.